The Frustrating Reality of Rising Auto Insurance Rates
You open your renewal notice and there it is—your premium went up, sometimes significantly. You haven't filed any claims, you didn't get any tickets, and your driving record is clean. So why are you paying more?
This frustrates drivers across California every day. You did everything right, yet your bill still increased. The answer isn't about you personally—it's about broader factors that affect everyone with auto insurance. Insurance companies adjust rates based on their overall costs, and those costs have been climbing steadily.
Understanding why premiums increase even for good drivers helps you make informed decisions about your coverage. Some factors you can control, but many you can't. What you can do is understand the reasons, shop strategically, and work with an agent who can help you find the best rates available for your situation.
Claims Trends and Industry-Wide Costs
Your individual driving record matters, but insurers set rates based on what's happening across their entire book of business. When claims costs rise industrywide, everyone's premiums tend to increase, even drivers who haven't filed claims themselves.
Auto accident frequency increased significantly in recent years. Even though people drove less during certain periods, the accidents that did occur became more severe. Medical costs for injured parties keep climbing, and vehicles sustain more damage in crashes than they used to because modern cars have more complex systems and expensive components.
Vehicle repair costs have skyrocketed. Your car contains advanced technology that costs substantially more to fix than older vehicles. Cameras, sensors, and computer systems that support safety features and driver assistance technologies aren't cheap to repair or replace. A fender bender that might have cost $1,500 to fix ten years ago can easily run $4,000 or more today.
Vehicle theft rates have also increased in many areas. Certain makes and models have become targets for organized theft rings. If you drive a vehicle that's frequently stolen, your comprehensive coverage premium reflects that higher risk. And catalytic converter theft has become an epidemic—these components contain valuable metals and can be removed in minutes, leaving you with a repair bill of several thousand dollars.
Medical costs continue their upward trajectory. When someone gets injured in an accident, the medical bills associated with their treatment increase year after year. California's medical cost inflation directly impacts auto insurance rates because personal injury protection and bodily injury liability coverage pay these bills.
Litigation trends affect premiums too. More accident victims hire attorneys, and settlements have grown larger. Legal costs, including both defense costs and settlement amounts, get built into everyone's premiums. California's legal environment and jury verdicts influence how much insurers need to charge to cover potential liability claims.
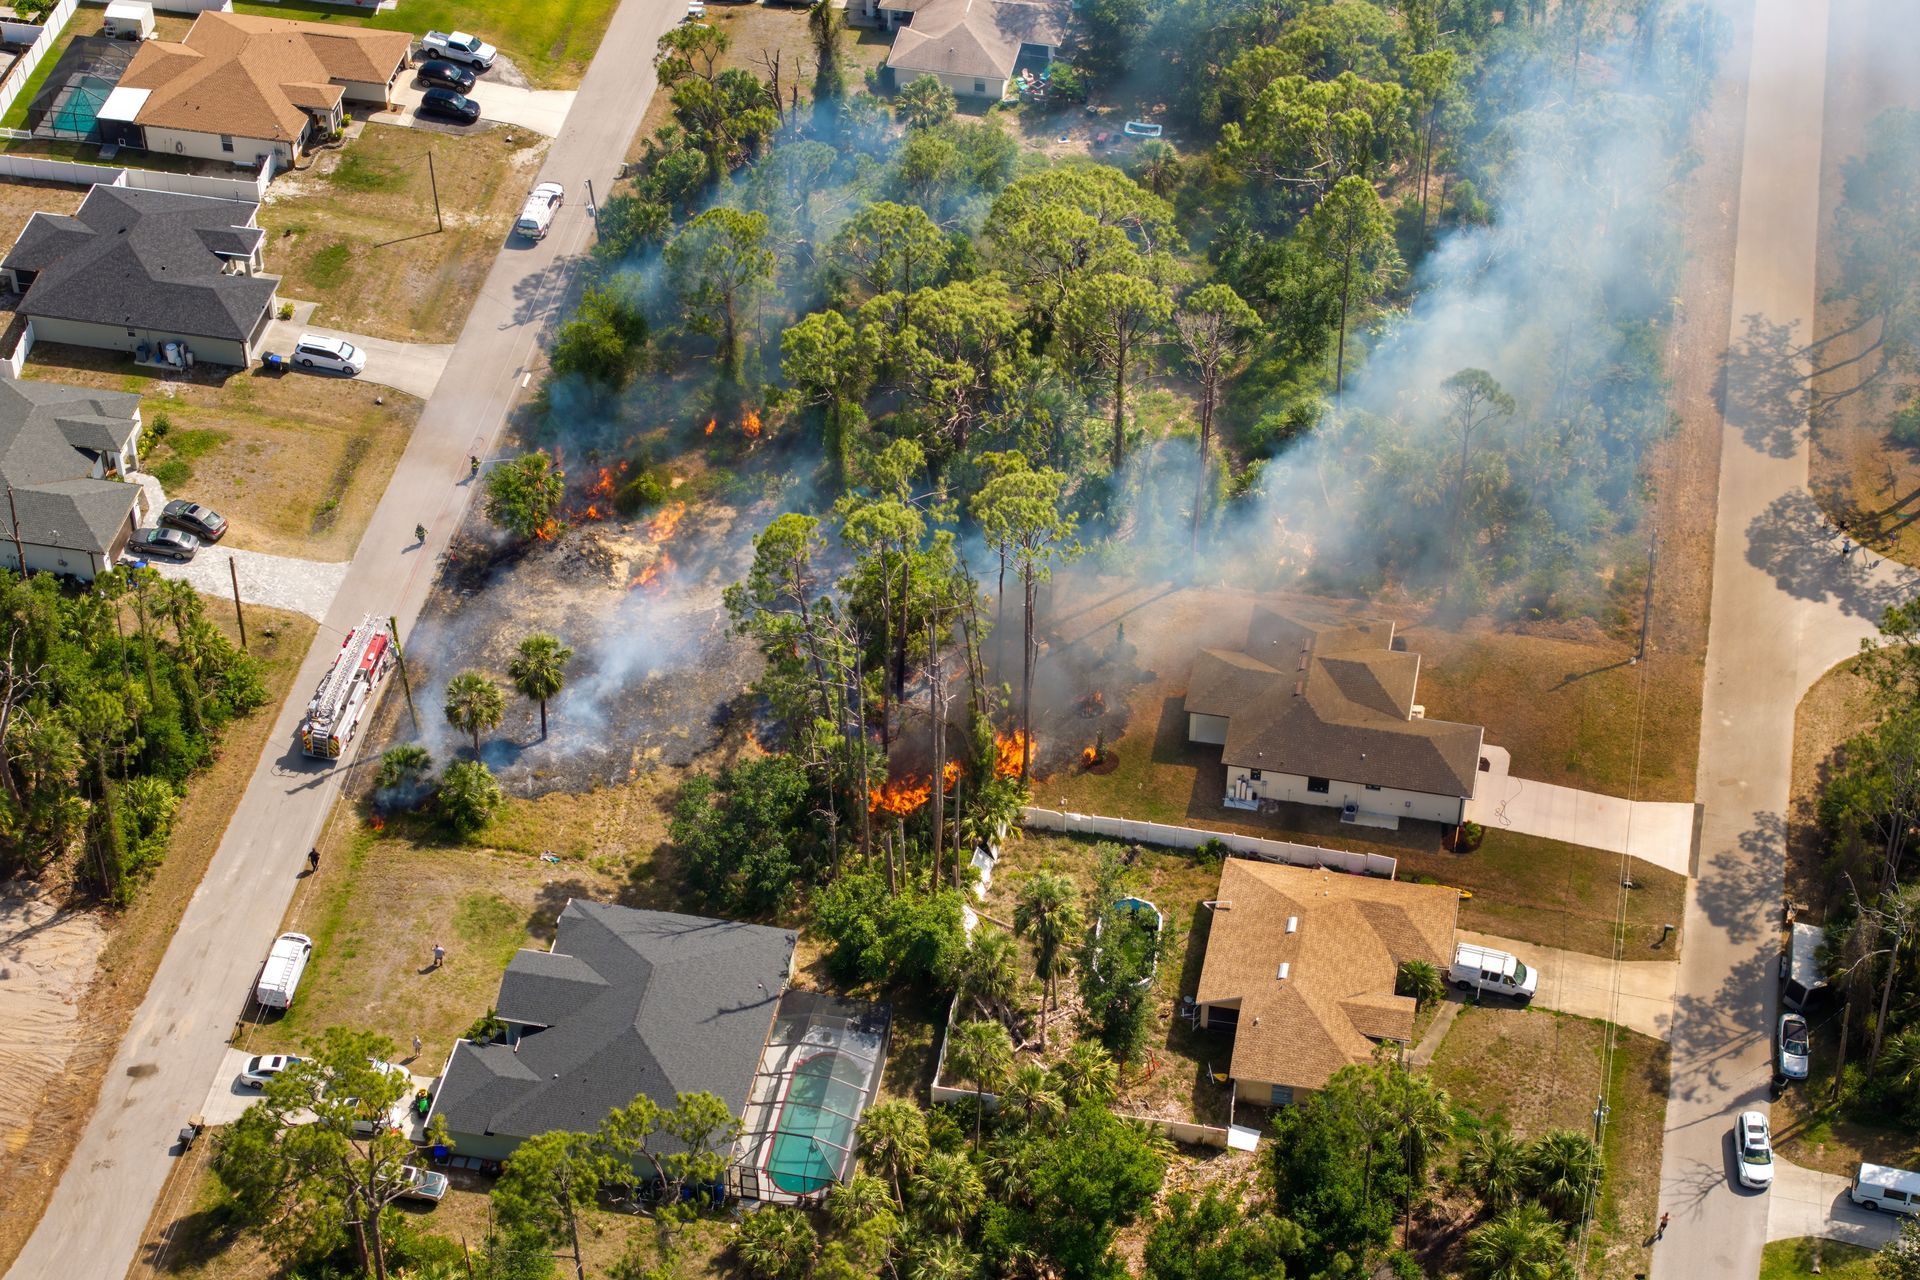
Natural disasters and weather events create additional costs. Wildfires, floods, and severe weather damage vehicles and increase comprehensive claims. Even if you personally weren't affected, the overall increase in weather-related claims across the state contributes to rate increases.
Economic Factors Beyond Your Control
Broader economic conditions influence auto insurance pricing in ways that have nothing to do with your driving behavior. Inflation affects insurance companies just like it affects every other business and consumer.
The cost of everything insurers pay for has increased—labor costs for claims adjusters and customer service representatives, the price of office space and technology systems, and vendor costs for repair shops and medical providers. These operational expenses get reflected in premiums.
Parts and materials shortages have disrupted the supply chain. When replacement parts are scarce, repairs take longer and cost more. Some vehicles have to be declared total losses because parts simply aren't available at reasonable prices. Extended rental car periods while waiting for parts add to claim costs.
Used car values surged to unprecedented levels. When insurers total a vehicle, they pay you its actual cash value. Higher used car prices mean higher payouts, which translates to higher premiums. Although used car prices have moderated somewhat from their peak, they remain elevated compared to historical norms.
Labor shortages at repair shops mean longer repair times and higher labor rates. Skilled technicians are in high demand, and shops have raised wages to attract and retain workers. These higher labor costs get passed along through increased claim costs and ultimately higher premiums.
Investment returns affect insurance pricing too. Insurance companies invest the premiums they collect, and investment income helps offset underwriting costs. When interest rates were near zero, insurers earned less on their investments and had to charge higher premiums to remain profitable. Interest rate changes impact pricing with a lag, so you might see effects from past investment conditions rather than current rates.
Regulatory requirements and state mandates also influence pricing. Changes to minimum coverage requirements, new regulations about how insurers can underwrite or rate policies, and state-specific requirements all affect what you pay. California's regulatory environment is particularly complex, and insurers must get rate changes approved by the Department of Insurance, which can delay necessary rate adjustments.
Credit Scores and Insurance Scoring Models
Your credit history affects your auto insurance premium in most states, including California, though many drivers don't realize it. Insurers use credit-based insurance scores as one factor in determining your rate.
Insurance scores differ from credit scores. They're based on your credit history but weighted differently to predict insurance risk rather than lending risk. Factors like payment history, outstanding debt, length of credit history, new credit applications, and types of credit used all contribute to your insurance score.
Research shows statistical correlation between credit characteristics and insurance claims. People with poor credit tend to file more claims than people with excellent credit, even when controlling for other factors. Insurers argue this makes credit a legitimate rating factor.
If your credit deteriorated—maybe you missed some payments, took on new debt, or maxed out credit cards—your insurance score could have dropped, leading to a premium increase. You might not have connected the two, but that financial stress that affected your credit also impacted your insurance rate.
Credit checks for insurance purposes are "soft pulls" that don't affect your credit score, but insurers typically recheck your credit at renewal. An annual review might reveal changes that affect your premium even if you didn't think anything changed with your insurance risk.
California places some limits on how insurers can use credit information, but credit-based insurance scores remain a significant rating factor for most companies. Improving your credit can help reduce your premiums over time. Pay bills on time, reduce outstanding debt, and avoid opening unnecessary new credit accounts.
Geographic Rating Factors
Where you live, work, and drive matters tremendously for auto insurance pricing. Your location determines a significant portion of your premium, and changes to geographic rating factors can increase costs even if you haven't moved.
Insurers divide geographic areas into rating territories, sometimes as specific as zip codes or even smaller areas. Each territory has its own rate based on claims experience in that area. If claims in your territory increased—maybe due to more accidents, higher theft rates, or increased vandalism—everyone in that area sees rate increases.
Population density affects rates. Urban areas with more traffic typically have higher rates than rural areas because more cars on the road means more accident opportunities. Congested traffic patterns, complicated intersections, and aggressive driving behaviors in cities all contribute to higher claim frequencies.
Crime rates in your area influence comprehensive coverage costs. Vehicle theft, vandalism, and break-ins vary widely by location. If crime increased in your neighborhood, your comprehensive premium likely increased too.
Commute patterns and traffic conditions change over time. If new development brought more traffic to your area, accident rates might have increased. Construction projects that create congestion and confusing traffic patterns can temporarily raise claims in an area.
Natural hazard exposure varies by location. Coastal areas face higher risk of flood damage, wildfire-prone regions see more comprehensive claims, and areas with severe weather experience more weather-related damage. Your location's exposure to these risks affects what you pay.
Local costs for medical care and auto repairs differ significantly across regions. The same accident injury that costs $20,000 to treat in one area might cost $35,000 in another due to different medical costs. Repair labor rates vary too. Insurers adjust premiums to reflect these local cost differences.
Changes in Rating Algorithms and Underwriting Models
Insurance companies constantly refine how they calculate premiums. They analyze vast amounts of data, identify new patterns, and adjust their pricing models accordingly. These changes can affect your premium even when your circumstances haven't changed.
Insurers develop more sophisticated models over time. As they gather more data and improve their analytics capabilities, they identify factors that predict claims risk more accurately. A model update might determine that certain characteristics previously thought to be low-risk actually correlate with higher claims, leading to rate increases for drivers with those characteristics.
New rating variables get introduced periodically. An insurer might start using factors they didn't consider before—perhaps job classification, homeownership status, or driving patterns tracked through telematics. If you fall into a category that's newly identified as higher risk, your rate could increase.
Competitive pressures influence pricing too. If an insurer priced coverage too aggressively to gain market share, they might need to raise rates once they realize they're not collecting enough premium to cover claims. You might have benefited from artificially low rates initially, and now you're seeing a correction.
Portfolio rebalancing happens when insurers decide they have too much exposure in certain markets or customer segments. They might raise rates on certain policy types or in certain areas to reduce their risk concentration, even if those policies are currently profitable.
Changes in reinsurance costs affect what you pay. Insurers purchase reinsurance to protect themselves against catastrophic losses. When reinsurance becomes more expensive—perhaps due to natural disasters elsewhere in the world—insurers pass some of those costs along through premium increases.
State Regulatory Approvals and Rate Filings
California requires insurers to file rate changes with the Department of Insurance and justify them. This regulatory process affects when and how much your premium can change.
Insurers must demonstrate that proposed rates are justified based on actual costs and anticipated claims. They submit detailed analyses showing why rate changes are needed. The Department reviews these filings and can approve, deny, or modify proposed rates.
Regulatory lag means insurers can't always adjust rates as quickly as their costs change. If claim costs increased rapidly, an insurer might be losing money for a period while waiting for approval to raise rates. Once approval comes through, the rate increase might seem sudden even though the underlying cost pressures built up gradually.
Some rate increases are "catch-up" adjustments. If an insurer's previous rates were inadequate and they've been losing money on auto insurance, they'll eventually need to raise rates substantially to return to profitability. You might experience a larger-than-usual increase as the company corrects past underpricing.
Regulatory decisions about which rating factors insurers can use also matter. If the state restricts certain rating variables, insurers adjust other factors to compensate. These shifts in how rates are calculated can affect your premium even if the overall average rate stays similar.
Understanding that your insurer can't arbitrarily raise rates helps provide context. Rate increases go through a formal approval process designed to ensure they're justified. But that doesn't make the increases any less frustrating when you're writing the check.
What You Can Actually Control
While many factors driving premium increases are beyond your control, you're not completely helpless. Several strategies can help you manage your auto insurance costs.
Maintain a clean driving record. This one's obvious, but it's also the most important. Avoid tickets, accidents, and claims whenever possible. Even an at-fault accident from years ago eventually falls off your record, so every year without incidents helps.
Review your coverage regularly. You might be carrying coverage you don't need. If you're driving an older vehicle with minimal value, dropping collision and comprehensive coverage could save money. Just make sure you can afford to replace the vehicle yourself if you do this.
Increase your deductibles if you can afford higher out-of-pocket costs when you file a claim. Raising your deductible from $500 to $1,000 can reduce your premium noticeably. Just make sure you have the funds available to pay the deductible if you need to file a claim.
Bundle your policies to get multi-policy discounts. Combining your auto insurance with homeowners or renters insurance from the same carrier typically saves you money on both policies.
Ask about available discounts. Many insurers offer discounts you might not know about—good student discounts, defensive driving course discounts, low mileage discounts, pay-in-full discounts, paperless billing discounts, and more. Make sure you're getting every discount you qualify for.
Consider usage-based or telematics programs if you're a safe driver who doesn't drive much. These programs monitor your driving habits and can provide significant discounts if you drive safely and infrequently. Privacy-conscious drivers might not like being monitored, but the potential savings are substantial for good drivers.
Improve your credit score. Since credit-based insurance scores affect your rates, working on your overall financial health can reduce your premium over time. Pay bills on time, pay down debt, and avoid unnecessary new credit applications.
Shop your coverage periodically. Different insurers use different models and weight factors differently. One company's rate increase might not match another's. Getting quotes from multiple carriers every few years ensures you're not overpaying. Working with an independent agent who represents multiple companies makes this process easier because they can compare options for you.
When to Shop Around vs. Stay Put
Just because your premium increased doesn't automatically mean you should switch insurers. Sometimes shopping around saves money, and sometimes it doesn't. Knowing when to compare options helps you make smart decisions.
Shop around when you experience a significant rate increase—generally anything over 10-15% without changes to your situation. A small increase might just reflect industrywide trends, but a large increase suggests it's worth checking if other insurers offer better rates.
Major life changes are good times to shop. If you moved, got married, added or removed drivers from your policy, bought a new vehicle, or experienced other significant changes, different insurers might rate these changes differently. Get new quotes to see if another carrier offers better pricing for your updated situation.
Don't shop immediately after an accident or ticket. Your rates will be high everywhere right after an incident. Wait until the incident ages on your record—usually at least six months to a year—before comparing options. By then, some insurers might rate that incident less severely than others.
Consider your overall satisfaction with your current insurer. Price matters, but so does service quality. If you've had good experiences with your insurer's claims service, that value shouldn't be dismissed lightly just to save $100 per year. On the other hand, if you've been dissatisfied with service, a rate increase might be the final push you need to switch.
Factor in loyalty discounts and accident forgiveness. Some insurers provide these benefits to long-term customers. If you're close to qualifying for accident forgiveness or a significant loyalty discount, staying might make sense even if rates increased slightly.
Understand how switching affects your coverage. Make sure you're comparing equivalent coverage when you shop. Sometimes a quote appears lower because the coverage isn't the same. Review limits, deductibles, and specific coverages to ensure you're making an apples-to-apples comparison.
Working with JMW Insurance Solutions, Inc. gives you access to multiple carriers through a single conversation. We can compare your current coverage against options from several insurers to determine whether switching saves you money without sacrificing coverage quality.
Frequently Asked Questions
Can my auto insurance go up without any tickets or accidents?
Yes. Insurers adjust rates based on factors beyond your individual driving record, including overall claims trends in their book of business, rising repair and medical costs, increased theft rates in your area, changes to your credit-based insurance score, and adjustments to their rating models. Even safe drivers with clean records can see premium increases when these broader cost factors change.
How much can my car insurance increase at renewal in California?
California doesn't cap how much insurers can raise your premium at renewal, but they must get rate changes approved by the Department of Insurance and justify them with data showing increased costs. Individual premium changes vary based on your specific rating factors, but increases of 5-20% aren't uncommon when insurers adjust rates. Larger increases can occur if your personal circumstances changed significantly or if you were previously receiving discounts that expired.
Is it worth switching car insurance companies for a lower rate?
Shopping around can save money, especially if your current rate increased significantly. However, consider factors beyond price—claims service quality, available discounts, coverage options, and convenience matter too. Get quotes that match your current coverage to make valid comparisons. If another insurer offers substantially lower rates for equivalent coverage (generally 15% or more savings), switching usually makes sense. An independent agent can help compare multiple carriers to find the best combination of price and coverage for your needs.